How Trade Credit Insurance Can Reduce Risk in Stainless Steel Cutlery Exports
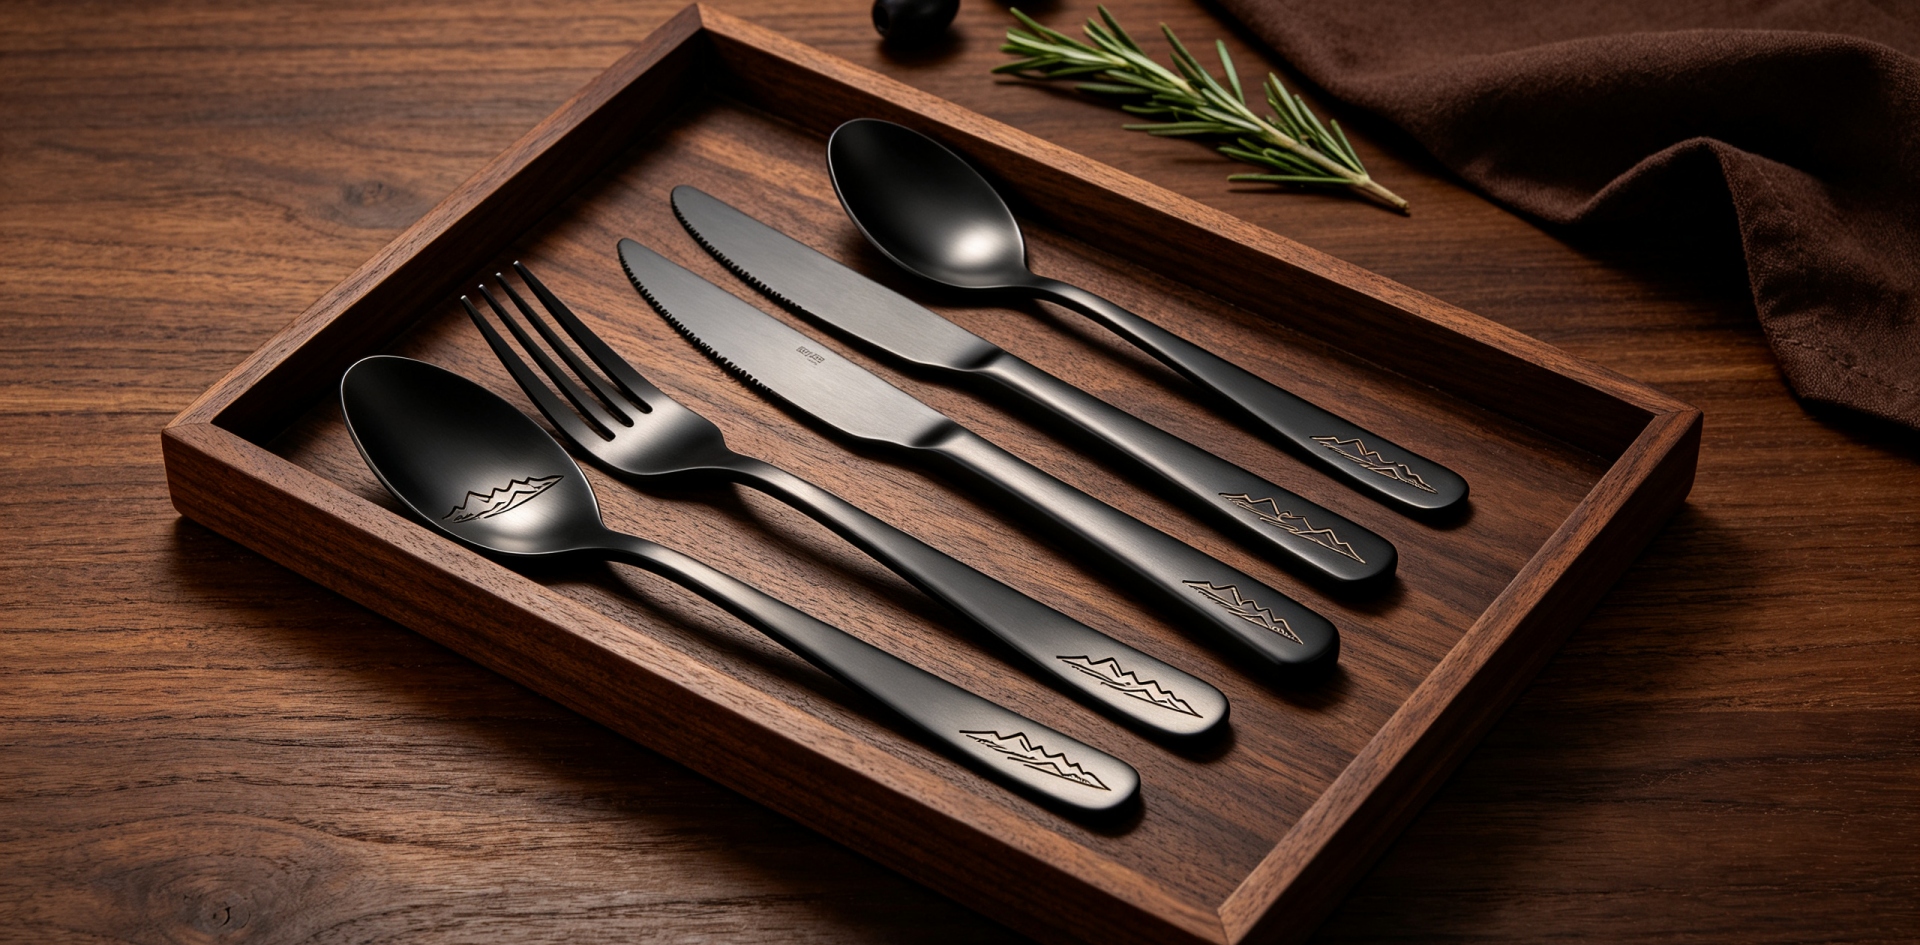
How Trade Credit Insurance Can Reduce Risk in Stainless Steel Cutlery Exports
Selling stainless steel cutlery to overseas distributors can create valuable long-term business, but it also exposes exporters to the risk of delayed or unpaid invoices. A buyer may have a strong sales network and a promising order forecast, yet still experience cash-flow pressure, customer defaults, or unexpected changes in market conditions.
For manufacturers and wholesalers supplying stainless steel spoons, forks, knives, and complete flatware sets, trade credit insurance may be one option for managing certain risks associated with selling on credit. It is not a substitute for customer assessment or sound payment terms. Instead, it can form part of a broader process for evaluating overseas buyers, setting credit limits, and protecting cash flow.
Why Credit Risk Matters in Stainless Steel Cutlery Exports
International cutlery orders can involve substantial commitments before the supplier receives full payment. The manufacturer may purchase materials, allocate production capacity, prepare custom tooling, complete polishing and finishing, and arrange packaging before the goods are shipped.
If the buyer receives the shipment but does not pay according to the agreed terms, the supplier may face both an unpaid receivable and reduced working capital for subsequent orders.
The exposure can be more complicated when an exporter serves several distributors in different countries. One customer may request longer payment terms, another may be expanding rapidly, and a third may depend heavily on a small number of retail accounts. Each relationship can present a different level of risk.
Trade credit insurance is designed to cover certain eligible receivables against specified risks, subject to policy terms, exclusions, waiting periods, and other conditions. Coverage varies by provider and contract, so exporters should not assume that every unpaid invoice or commercial dispute will qualify for reimbursement.
1. Understand the Difference Between Credit Assessment and Insurance
Before applying for trade credit insurance, exporters should understand what it does and what it does not do.
Credit assessment helps a supplier decide whether to sell to a customer on credit, how much exposure to accept, and what payment terms are appropriate. Trade credit insurance may provide an additional layer of protection for eligible losses if the buyer fails to pay for a covered reason.
Neither process guarantees payment in every circumstance. A financially stable customer can encounter difficulties, while an insured transaction can still fall outside the policy's scope if required conditions are not met.
For a stainless steel cutlery manufacturer, the first step is to establish a consistent customer review process. Consider the buyer's trading history, payment behavior, business stability, requested credit period, existing outstanding invoices, and the size of the proposed order relative to the customer's normal purchasing volume.
Insurance should support this assessment rather than replace it.
2. Evaluate Which Orders May Need Coverage
Not every stainless steel cutlery transaction has the same risk profile. A small trial order paid in advance may present limited receivables exposure, while a recurring wholesale program with a long credit period can create a larger amount of money at risk.
When reviewing potential coverage, consider:
-
The buyer's requested payment terms and credit period.
-
The total value of outstanding invoices.
-
The expected volume of repeat orders.
-
The buyer's country and relevant market conditions.
-
Whether the order involves standard products or customer-specific production.
-
The potential effect of non-payment on the supplier's working capital.
Custom OEM or private-label orders deserve particular attention. If a buyer defaults on an order of branded flatware sets, the exporter may have difficulty reselling the finished products to another customer. Credit insurance, where available, may address eligible receivables exposure, but it should not be assumed to reimburse every production cost or loss in resale value.
The exporter should evaluate these commercial risks separately when deciding whether to accept the order.
3. Review the Credit Limit and Coverage Conditions
A policy may set a maximum insured exposure for each buyer or apply other limits to eligible receivables. Exporters should confirm how the limit is established, when it becomes effective, and what happens if the buyer's outstanding balance exceeds it.
Suppose a stainless steel flatware supplier has an approved credit limit for a distributor. If new shipments and unpaid invoices cause the total exposure to exceed that limit, the excess amount may not receive the same protection. The precise outcome depends on the policy wording and any applicable approvals.
Before shipping, finance and sales teams should check the available credit limit against the customer's existing balance and the proposed invoice value. They should also understand any requirements concerning shipment dates, invoice submission, overdue notices, and reporting of significant changes in the buyer's financial condition.
A written procedure helps prevent a sales team from assuming that an order is fully covered simply because the customer has been approved previously.
4. Calculate the Commercial Cost of Coverage
Trade credit insurance has a cost, and exporters should evaluate it in relation to the risk being managed. Depending on the provider and policy, the total expense may involve premiums, minimum charges, administration, deductibles, or other contractual costs.
A useful starting point is to compare the estimated cost of coverage with the value of the receivables being protected and the potential financial effect of non-payment. This should be a business decision based on realistic assumptions rather than a guarantee that the policy will generate a positive return.
For example, an exporter selling stainless steel spoons and forks to several wholesale customers may compare the cost of coverage with its expected credit sales, historical payment performance, and concentration of receivables among major buyers.
The calculation should also consider the supplier's ability to absorb a loss. A large unpaid invoice may create more serious pressure for a small manufacturer than for a business with substantial cash reserves and diversified sales.
Insurance pricing and coverage should be reviewed with a qualified provider or broker, especially when the business exports to multiple markets.
5. Coordinate Insurance With Payment Terms and Order Release
Credit insurance works best when the supplier's sales process follows the policy's requirements. Payment terms, invoice timing, shipment release, and overdue-account handling should be coordinated rather than managed independently by different departments.
For example, a supplier may offer an approved distributor a deposit arrangement followed by a balance payable within an agreed period after shipment. The actual terms should reflect the customer's credit assessment, the commercial agreement, and any relevant insurance conditions.
Before releasing a stainless steel cutlery shipment, confirm that the purchase order and invoice match the agreed buyer identity, currency, amount, and payment terms. Keep the relevant shipping and delivery records, since supporting documents may be important if a claim is submitted later.
If a customer requests a longer payment period or a substantial increase in order quantity, review the credit exposure before accepting the change. A previously approved customer should not automatically receive unlimited additional credit.
6. Maintain Records for Overdue Accounts and Potential Claims
Documentation is essential when managing international receivables. Exporters should maintain a clear record of invoices, purchase orders, shipping documents, delivery evidence, payment receipts, correspondence, and any agreed changes to the original terms.
When an invoice becomes overdue, the finance team should follow the company's collection procedure and the insurer's notification requirements where applicable. Waiting too long to report a problem can affect eligibility for coverage, depending on the policy.
A practical overdue-account file should identify the invoice amount, due date, outstanding balance, collection actions, buyer responses, and any disputes. If the buyer challenges the product specifications, quantity, packaging, or delivery, the exporter should document the issue and review the contractual evidence before determining the next step.
Insurance claims often depend on specific timelines and supporting documents. The supplier should follow the policy rather than assume that an informal email or a general payment reminder will satisfy every requirement.
7. Integrate Credit Risk Into Distributor Management
Trade credit decisions should be reviewed throughout the relationship, not only when the first order is placed. A distributor's purchasing volume may increase quickly, but higher sales do not necessarily mean lower credit risk.
Set periodic reviews for customer balances, overdue invoices, payment patterns, and changes in the buyer's business. If one distributor represents a large share of export revenue, assess the concentration risk and consider whether exposure should be distributed across additional customers or markets.
For stainless steel cutlery programs, purchasing teams should also monitor custom inventory commitments. A large order of branded knives, forks, and spoons may involve costs that cannot easily be recovered if the buyer becomes insolvent or refuses delivery.
Homefelt works with B2B buyers on stainless steel cutlery manufacturing, wholesale supply, and OEM or ODM customization. Clear communication about product specifications, order quantities, packaging, delivery schedules, and payment arrangements helps establish a more transparent commercial foundation. Credit decisions and insurance coverage, however, should be assessed separately by the parties responsible for their financial risk.
Conclusion
Trade credit insurance can be a useful risk-management option for eligible stainless steel cutlery export receivables, but its value depends on the buyer, order size, policy terms, and the supplier's existing credit controls.
Exporters should combine customer assessment, appropriate payment terms, documented shipment procedures, timely overdue-account reporting, and regular exposure reviews. Before purchasing a policy, confirm its limits, exclusions, notification requirements, and claims process with a qualified insurance provider.
For B2B buyers seeking stainless steel spoons, forks, knives, and customized flatware sets, Homefelt can discuss product specifications, wholesale quantities, OEM or ODM requirements, packaging, and transportation planning. To request a quotation or discuss a new project, contact ingrid@homefelt.net with your product requirements and target order volume.
You May Be Interested In
-
How to Assess Customer Credit Terms for Stainless Steel Cutlery B2B Orders
-
How to Plan Payment Milestones for Stainless Steel Cutlery OEM Projects
-
How to Evaluate a Trial Order Before Expanding a Stainless Steel Cutlery Supplier Partnership
-
How to Build a Purchase Order Approval Workflow for Stainless Steel Cutlery
How to Calculate the Cost of Poor Quality in Stainless Steel Cutlery Orders
How to Control Order Cancellation Costs in Stainless Steel Cutlery Procurement
Related Article